Categories
 Sarees
 Women’s Wear
 Men's Wear
TOP RATED PRODUCTS
-
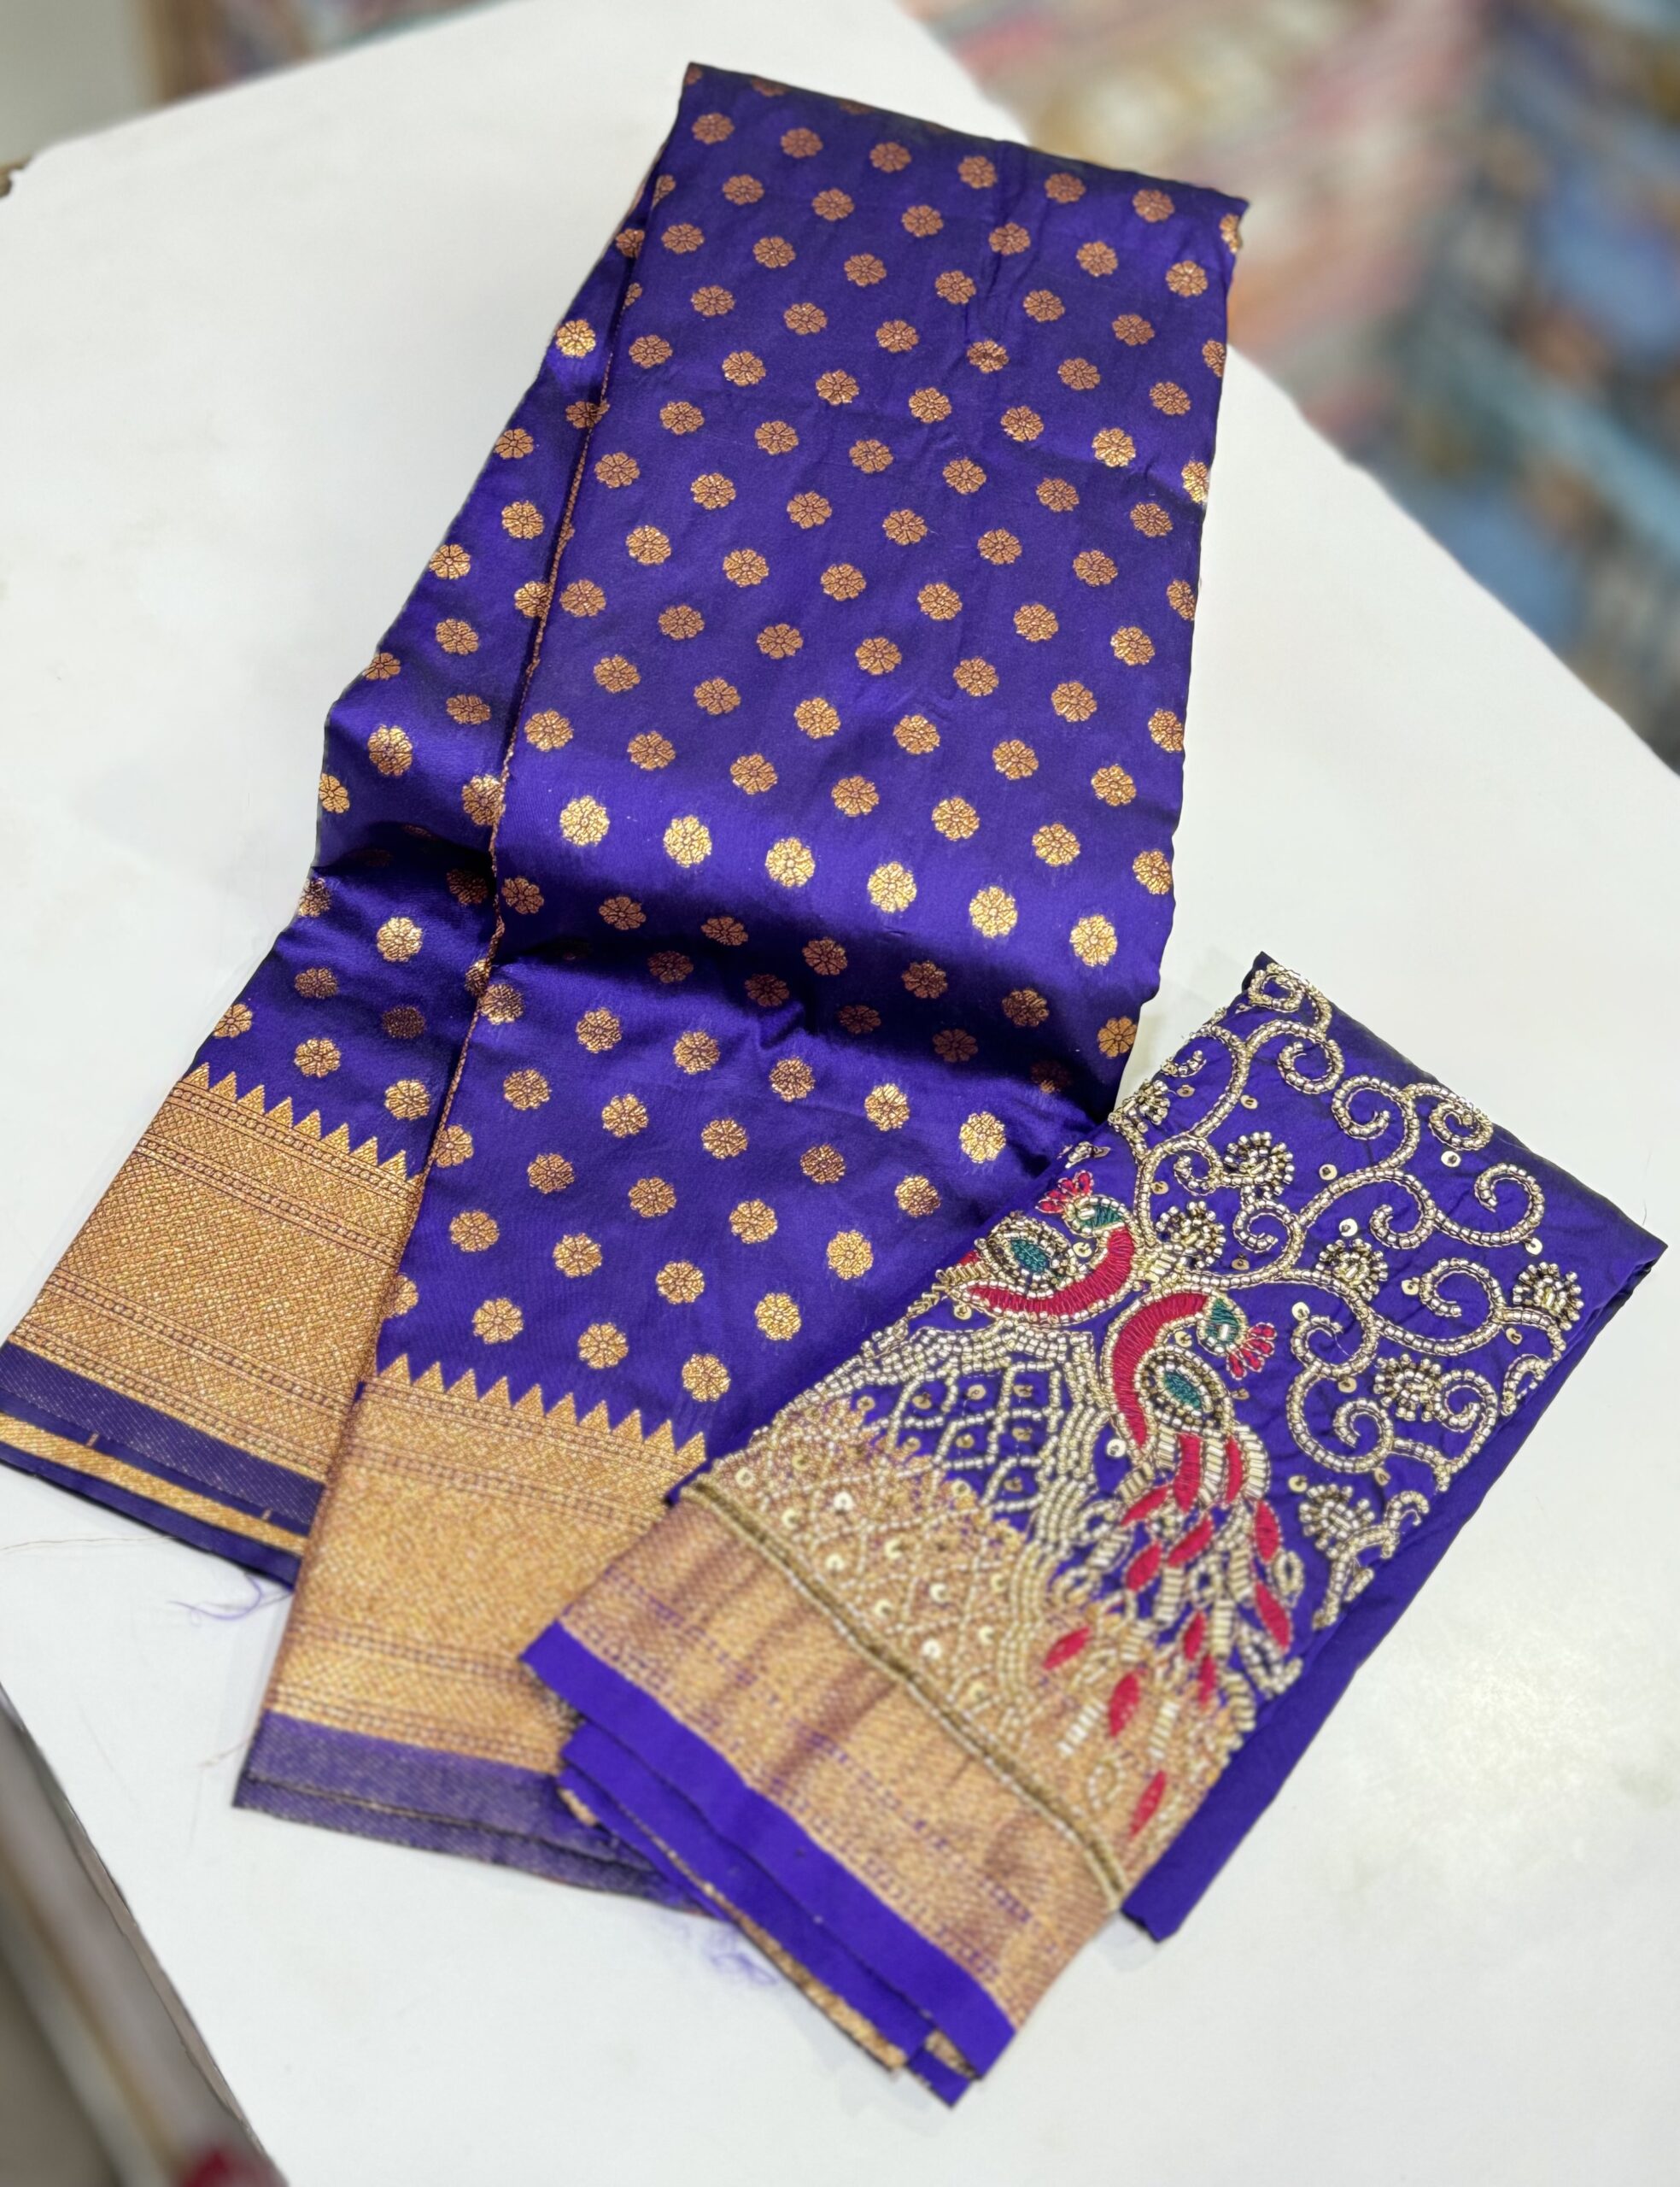
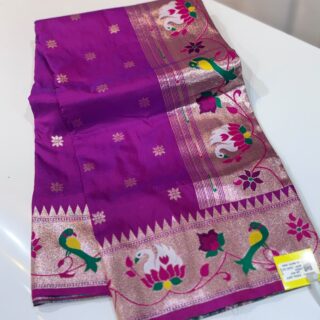 Rajhuns paithani #jh106
Original price was: ₹1,499.00.₹850.00Current price is: ₹850.00.
-
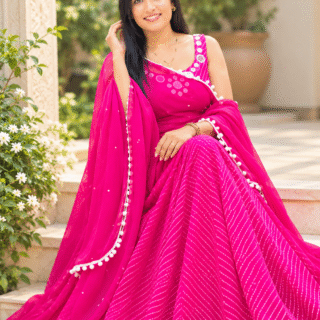 lehriya anarkali pattern #jh111
Original price was: ₹2,600.00.₹1,400.00Current price is: ₹1,400.00.
-
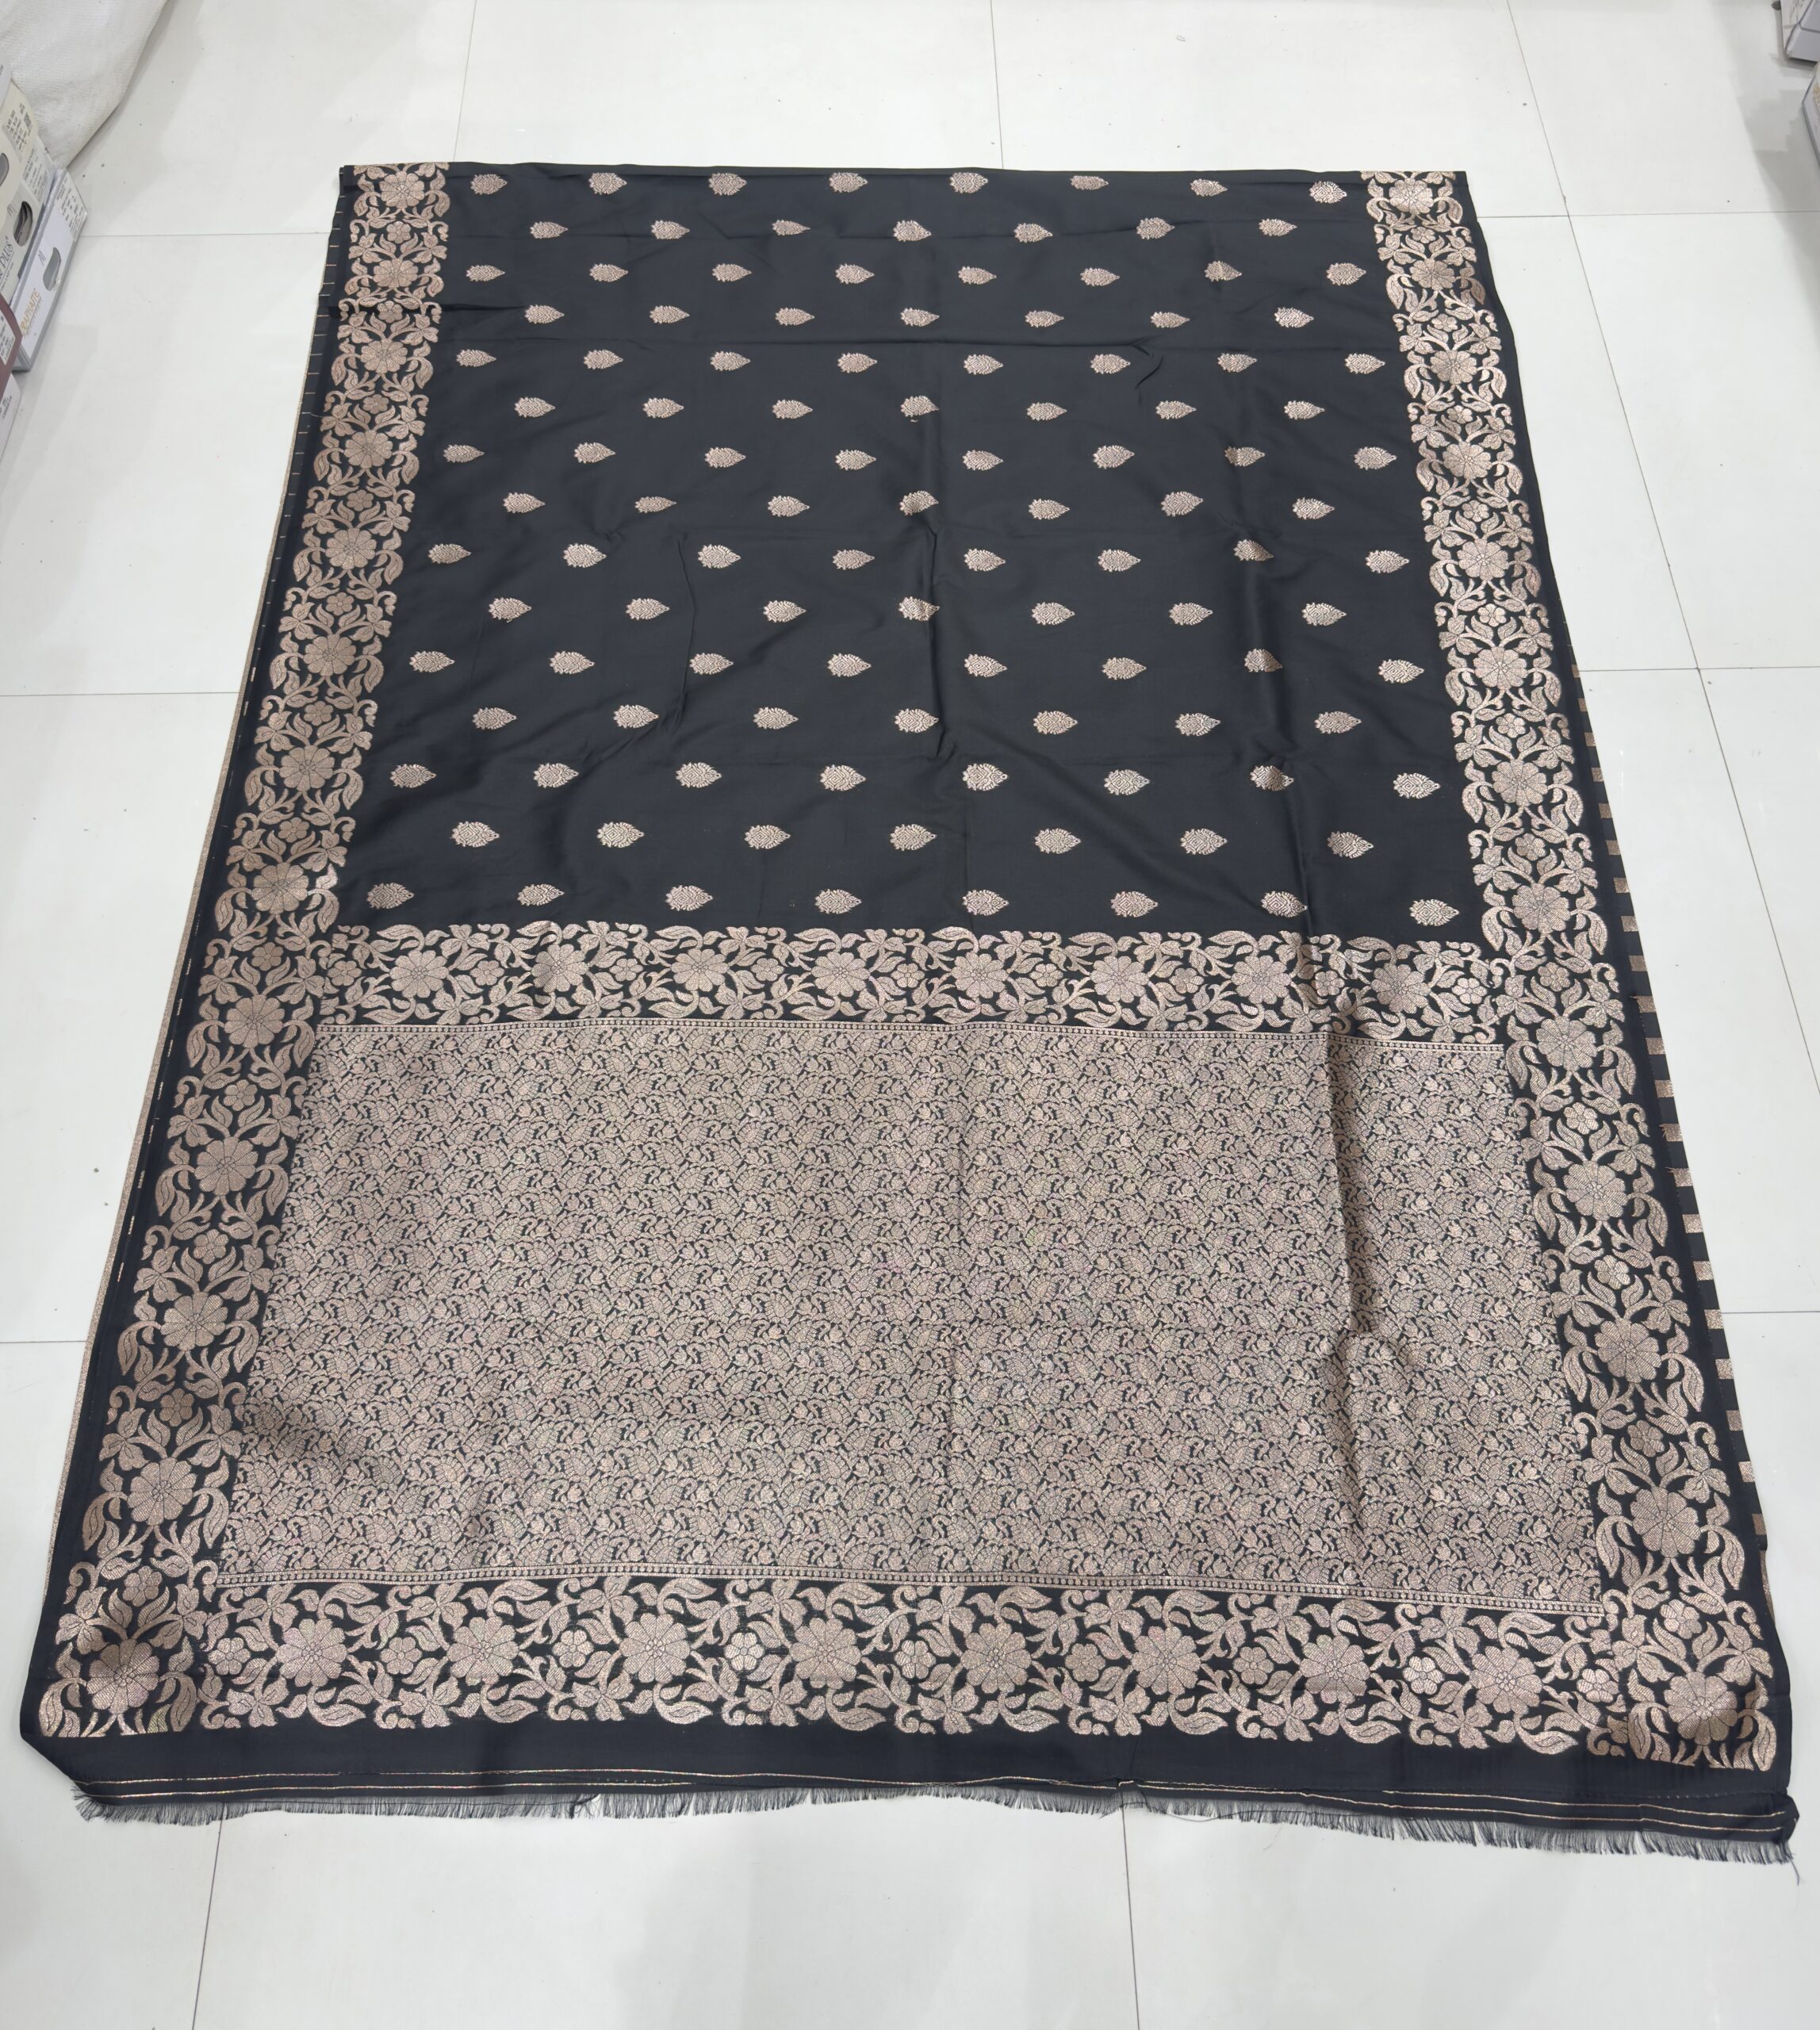
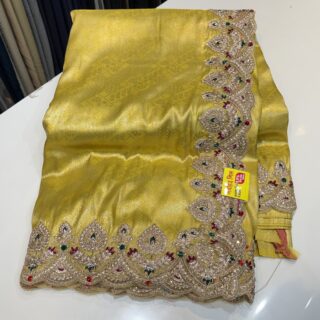 New designer saree #jh110
Original price was: ₹3,700.00.₹2,500.00Current price is: ₹2,500.00.
-
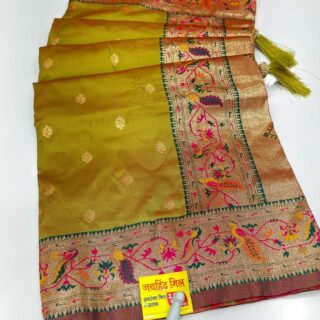 Lotas border saree #jh109
Original price was: ₹1,950.00.₹1,000.00Current price is: ₹1,000.00.
-
 3 pis #jh108
Original price was: ₹1,500.00.₹950.00Current price is: ₹950.00.
GALLERY
CLIENT'S TESTOMONIAL
Preeti
Amazing collection and great pricing! The designs are unique, and delivery was super fast.
Rohini
Absolutely love the quality of Jai Hind Mills sarees! The fabric is so soft and elegant. Will shop again!
When you initiate a withdrawal from your financial account, you might find it doesn’t show up in your bank instantly. This waiting period often puzzles users who anticipate quick processing. Understanding the purpose of sites not on GamStop helps shed light on why financial institutions put in place these processing times and what happens internally during this period. Various factors including security measures, account verification, and compliance rules affect these timeframes, which can range from a few hours through several business days depending on your bank and payment method.
What Are Pending Withdrawal Periods and Why Do They Exist
A pending withdrawal period represents the duration between initiating a withdrawal request and when funds exit the system infrastructure. During this window, banking entities execute necessary security checks, validate account authenticity, and ensure compliance with regulatory standards that safeguard both parties participating in the transaction.
These mandatory delays serve chiefly as fraud prevention and security management purposes. Financial platforms leverage this period to detect suspicious activity patterns, confirm user identity through various verification methods, and assess transactions that might activate automated security alerts or require manual oversight from compliance staff.
Additionally, pending periods support the processing systems required for handling withdrawal requests across different payment systems. Banks and payment processors operate on specific settlement schedules, and integration of various banking platforms creates wait times that institutions build into their withdrawal processing schedules.
Standard Factors That Affect Your Payout Transaction Time
Multiple factors influence how quickly your withdrawal request moves through the processing pipeline. Financial institutions must balance speed with security, compliance requirements, and operational efficiency. Grasping these considerations helps create reasonable expectations for when funds will be available in your account.
Each withdrawal undergoes a range of verification steps and procedures that vary based on your individual situation. The processing duration depends on banking institution guidelines, the nature of your transaction, and external banking systems. Being aware of these variables enables you to organize your finances with greater efficiency.
Verification and Security Checks
Financial institutions establish rigorous protective protocols to shield both your assets and their systems from fraudulent activity. Every withdrawal request triggers both automated and manual confirmation procedures that confirm your identity and confirm the authenticity of the transaction before funds are released.
These security measures include reviewing account activity patterns, verifying login credentials, and identifying suspicious withdrawal activity. While these verification steps extend processing timelines, they safeguard your money from illicit transactions and ensure compliance with anti-money laundering regulations that banks are required to observe.
Deposit Method and Financial Networks
The payout method you select significantly impacts transaction speed, as different payment channels operate on distinct technological infrastructures. Bank transfers depend on interbank networks that handle payments in groups, while e-wallets may offer faster processing through seamless integration with financial platforms.
Conventional financial networks often operate only within standard operating hours and exclude weekends and holidays, causing inevitable delays in transaction processing. International transfers involve additional intermediary banks and currency conversion systems, which prolong the duration versus domestic transactions within the same banking network.
Withdrawal Sum and Account Standing
Higher withdrawal amounts typically demand further scrutiny and approval from management officials within the financial institution. Transactions surpassing specific thresholds activate strengthened due diligence procedures intended to combat fraudulent activity, meet reporting requirements, and guarantee proper liquidity management.
Your account history and standing can affect processing speed, as accounts in good standing with consistent activity patterns often get faster approvals. New accounts, accounts with recent changes, or accounts with minimal activity records may face extended review periods as institutions confirm authenticity and build confidence through tracking transaction patterns.
Common Withdrawal Pending Timelines by Payment Option
Multiple payment approaches feature different processing speeds based on their technical framework and security checks. Bank transfers typically involve extended timeframes because they involve multiple intermediary institutions and compliance checks before funds arrive in your account. Electronic wallets and e-wallet systems often handle payments more rapidly due to their streamlined systems, though they continue to demand security verification steps that can extend the timeframe to your transaction.
The processing period for your withdrawal varies considerably on whether you’re using conventional banking methods or contemporary electronic payment options. Credit card refunds usually take longer as they must go back via the original transaction pathway and wait for billing cycle updates. Wire transfers are often rapid for domestic transactions but international transfers may require more time for currency exchange and international compliance processes.
Understanding these differences helps you prepare in advance when starting withdrawals from your accounts. Most money management sites provide projected timelines during the withdrawal process, but actual processing periods may vary based on weekends, holidays, and your specific financial institution’s processing schedule. Choosing the right payment method for your needs weighs convenience with the urgency of accessing your funds.
- Bank transfers: 3 to 5 business days generally
- E-wallets: 1 to 3 business days typically
- Credit cards: 5 to 10 business days standard
- Wire transfers: 1-2 days domestically
- Cryptocurrency: 1-24 hours depending on conditions
- Checks: 7-14 business days typically
Projected Processing Timeframes for Various Types of Withdrawals
Different payout options have varying turnaround periods based on their foundational systems, safety protocols, and company guidelines. Understanding these timeframes helps you budget effectively better and set realistic expectations when processing withdrawals. The turnaround period depends on factors such as the payment system employed, whether transfers occur during business hours, and the authentication procedures required by your financial institution.
| Withdrawal Method | Typical Processing Time | Business Days Required | Additional Factors |
| Bank Transfer (ACH) | 1-3 business days | 1 to 3 days | Weekends and holidays extend timeframe |
| Wire Transfer | Same day or 1 business day | 0 to 1 days | Cut-off times apply and international transfers may require additional time |
| Digital Wallets | Immediate to 24 hours | 0-1 days | Relies on wallet provider and verification status |
| Check | 5-10 business days | 5 to 10 days | Includes postal delivery and bank clearing period |
| Cryptocurrency | 15 minutes to 2 hour timeframe | 0 days | Network congestion and confirmation requirements vary |
Electronic transfers through automated clearing house networks generally take one to three business days because they process in batches rather than individually, enabling banks to handle large volumes effectively.
Wire transfers generally complete quicker than ACH transfers, frequently completing within the same business day if initiated before the bank’s cut-off time, though they typically carry higher costs for this faster option.
How to Accelerate Your Payout and Avoid Slowdowns
Finalize your account verification prior to submitting withdrawals to eliminate the most common delay factor. Confirm all identity documents are up-to-date and provided beforehand, including proof of address and payment verification. Many platforms give priority to verified accounts, allowing them to bypass additional security checks that can lengthen wait times significantly.
Choose quicker payout options such as e-wallets or cryptocurrency options when available, as these generally complete much quicker than conventional wire transfers. Check your organization’s pricing model, as accepting somewhat elevated processing fees often enables entry to faster payout options. Plan your withdrawals during standard business hours on weekdays to prevent weekend and holiday delays.
Uphold steady withdrawal habits and avoid requesting amounts that initiate extra compliance checks, which usually happen with exceptionally large or frequent transactions. Keep your contact details up to date so institutions can reach you quickly if verification is required. Familiarize yourself with your platform’s specific withdrawal policies and processing schedules to time your requests optimally.

ABOUT US
Jai Hind Mills – A trusted name in premium textiles, blending tradition with innovation to deliver superior quality fabrics.
FEATURED PRODUCTS
AD WIDGET
FROM THE BLOG
Step into the world of elegance and tradition with Jaihind Mill’s exclusive saree collection. Whether you’re looking for a classic silk saree, a trendy designer drape, or a light and comfortable daily wear, we have something special for every occasion — and now, you can shop it all online! Our saree collection is carefully curated …
Beautiful Saree Collection Now Available Online – Shop at Jaihind MillRead More
Leave a Reply